


-RATED BY

Built in Canada
All Ecoline windows and doors are built in Ontario, Canada
- Top-of-the-line machinery (Forel, Gracco, Bottero) to produce the best products
- Over 60,000 sq. ft manufacturing plant
- Energy Star-rated and NAFS-11-tested
- Manufactured for local weather conditions
5 Reasons to Finance Window Replacement in Canada (Even If You Have Savings)
Nov 17, 2026
13 min read
19
Replacing 10 or 12 windows can quickly turn into a five-figure home renovation project. Even if you have enough savings, paying $12,000 or more all at once might not be the best financial move.
Think about buying a car for a second. Even with $25,000 saved, you probably wouldn’t spend all your money just to avoid monthly payments, especially if those savings are also your emergency fund.
Window replacement is similar since the typical project itself is costly. Financing lets you spread out the cost of an upgrade you’ll use for years, making payments more manageable. It can also help you replace all the windows you need now, instead of delaying part of the project.
However, not all financing options are the same. Today, our experts break down the real costs, benefits, and protections each payment plan might offer and how it works for Canadian homeowners.

Why Financing Windows Can Make More Sense Than Paying Everything Upfront
The main benefit of financing isn’t just being able to afford new windows. It’s about keeping better control of your money while making a key upgrade to your home.
Let’s look at three homeowners who are all planning a standard full home window replacement project quoted at $12,000:
| Homeowner | How they pay | Outcome |
| A | Uses $12,000 in savings | No interest, but $12,000 less available for emergencies |
| B | Replaces only six windows for $6,000 | Spends less today but leaves the remaining windows for another project |
| C | Finances all 12 windows | Keeps savings available and completes the project, but pays interest over time |
If Homeowner A has enough savings after setting aside an emergency fund, paying upfront is likely the best choice.
But for Homeowner C, it might be better to finance if the other option is using up most of their savings or leaving important work undone.
The real question isn’t just if you can afford new windows right now. It’s how paying for them will impact your finances later.
What Does Financing a $12,000 Window Replacement Actually Cost?
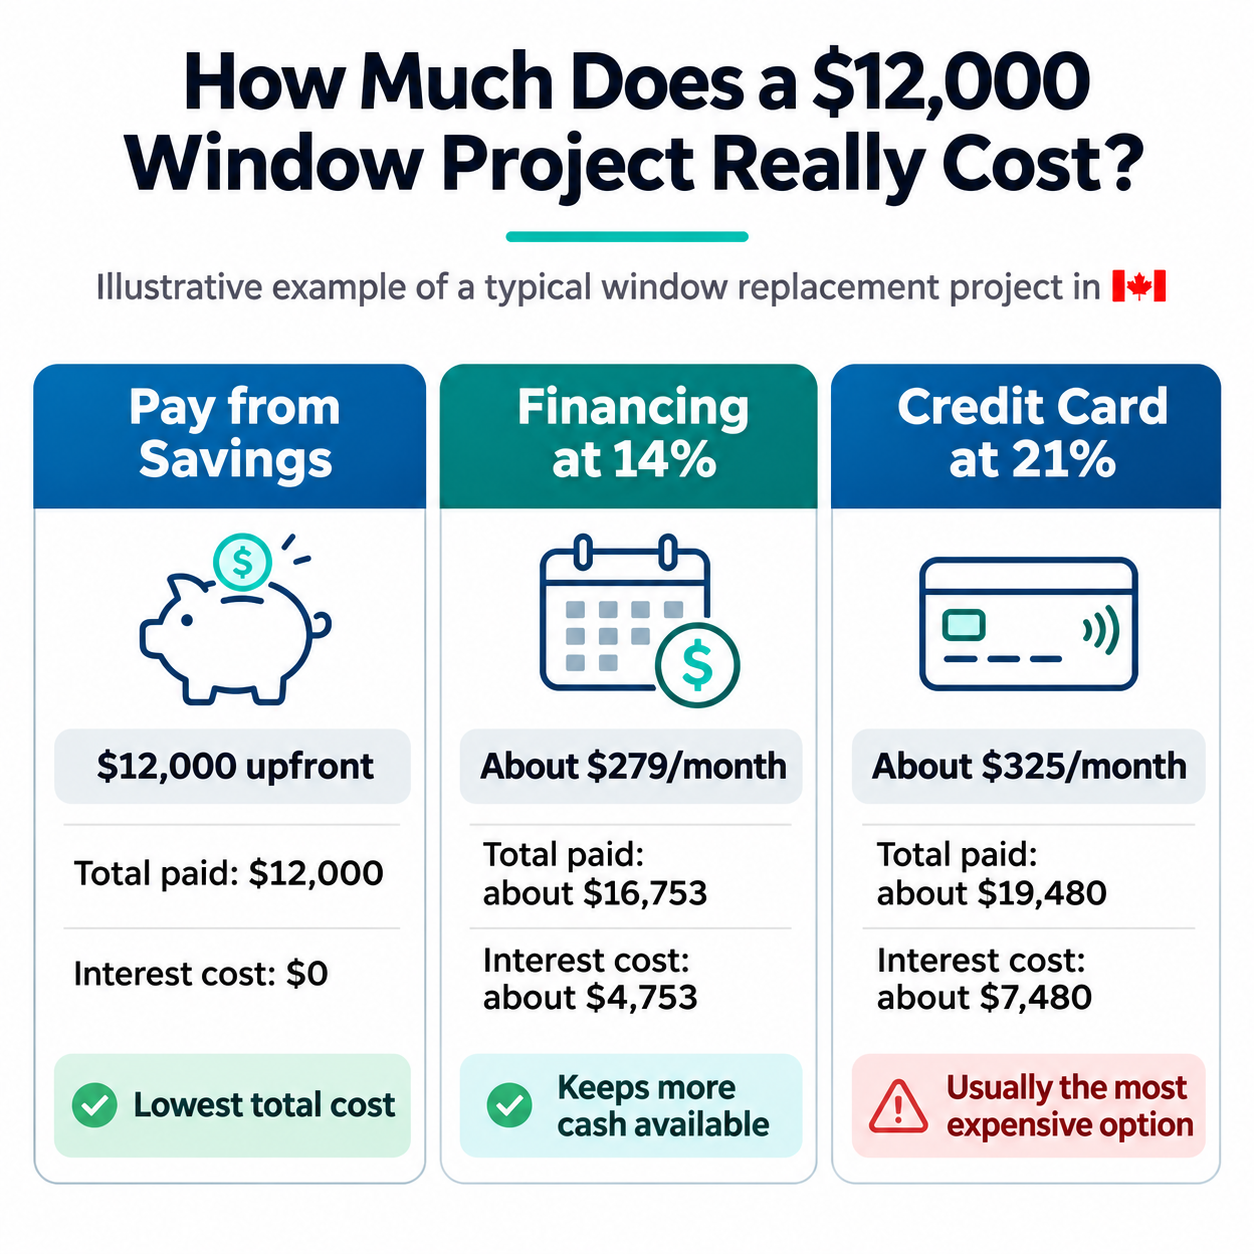
Let’s look at some real numbers here. Say you’re replacing 12 windows for $12,000, including installation. You could pay all at once, get a five-year home improvement loan, or use a credit card.
Here’s a comparison of those options:
| Payment method | Monthly payment | Total paid | Interest cost |
| Pay from savings | $12,000 upfront | $12,000 | $0 |
| Financing at 14% | About $279 | About $16,753 | About $4,753 |
| Credit card at 21% | About $325 | About $19,480 | About $7,480 |
Illustrative calculations based on a $12,000 balance, fixed annual interest rates, and 60 equal monthly payments, with no additional fees or promotional deferral. These are not advertised Ecoline financing rates.
The difference is significant. With these numbers, financing at 14% costs about $2,700 less in interest than using a credit card at 21%.
While paying cash is cheapest overall, making $279 monthly payments might be easier than taking out $12,000 all at once. Of course, financing comes with a cost. That extra $4,753 is what you pay in interest over five years.
So to stay safe here, homeowners need to decide if keeping their savings and finishing the renovation sooner is worth paying that extra amount.
5 Reasons Financing Your Windows May Be the Smarter Decision
1. You keep your emergency savings available
For example, you have $15,000 in savings and get a $12,000 quote for window replacement. Technically, you can afford the project. But afterward, you’d be left with just $3,000.
What if your furnace breaks down in February or your car suddenly needs a $2,000 repair? Financing helps you keep more cash on hand for unexpected expenses.
This doesn’t mean borrowing is always better than using your savings. You should still weigh the loan’s interest cost against your own finances. Still, having an emergency fund is valuable, even if it’s not shown in a contractor’s quote.
2. You can replace all the windows that need attention
A common compromise during renovations is cutting back the project to match the cash you have right now. For instance, you might replace six windows this year and wait two or three years to do the rest.
This approach works if only a few windows really need replacing. But if all 12 have issues like bad seals, drafts, or damaged frames, splitting the project means you’ll keep dealing with those problems.
| Replace in two stages | Replace all windows at once with financing |
| Smaller initial expense | Higher total project value |
| Some old windows remain | All necessary windows addressed together |
| Another project must be scheduled later | One coordinated replacement project |
| Future installation prices may change | Current quoted scope can be completed now |
Financing can also help you choose the right glazing, installation methods, and other important features, instead of picking the cheapest options just to fit your current budget.
The point isn’t to buy extras you don’t need. It’s to make sure you don’t have to cut corners on a renovation that’s already necessary. Don’t forget that windows are usually a once-in-a-lifetime purchase since modern high-end vinyl windows can serve you for 25 years at the very least.
3. You don’t have to wait years while your windows get worse
Not all old windows need to be replaced right away. But if your windows leak, let in drafts, or have damaged frames, waiting to fix them can let those problems get worse.
Natural Resources Canada identifies windows, doors, and skylights as a significant source of residential heat loss of up to 25%. It also notes that window improvements can include repairs, weatherstripping, glazing upgrades, or complete replacement, depending on their condition.
Financing can be a good option when replacement is needed and waiting would mean living with discomfort or ongoing issues.
While energy savings alone won’t cover your financing payments, new energy-efficient windows can help reduce heating and cooling costs over time. Depending on your existing windows and home’s efficiency, these savings could reach up to 12%, helping offset part of the overall replacement cost.
4. You get years of use while paying over a shorter period
A well-chosen and installed window system can last for decades, though its lifespan depends on quality, maintenance, and exposure. Now think about that compared to a five-year repayment plan.
You could spend five years paying for an upgrade you’ll use for 20 years or more. It’s a bit like financing a car, except windows are a permanent part of your home, not something you replace often.
You’ll still pay interest, but this shows why financing a long-term home upgrade can make more sense than borrowing for something short-lived.
5. A zero-down-payment program can reduce your upfront risk
Deposits are another key thing to think about when choosing a window replacement company. Custom windows are usually made after you place your order, and some contractors ask for large deposits before they start production. This means you’re committing some of your money before the work is finished.
A real example from Canada shows why this is important:
- In 2024, customers of one window company in NS reported losing access to deposits after the company suspended operations with one customer who had paid more than $10,000 for windows that were never installed.
A financing plan with $0 down and nothing due on installation day means you don’t have to pay a big deposit upfront. At Ecoline, eligible homeowners can get zero-down-payment programs, depending on the financing agreement and current offers you can check here.
However, financing doesn’t guarantee protection if the contractor doesn’t finish the job. You should check when the lender releases funds, when you start repaying, and what happens if the installation is cancelled or there’s a dispute.
What Does “12 Months No Payments” Actually Mean?
This is an area where homeowners should be especially careful. Two companies might both offer a 12-month payment deferral, but the financing terms can be very different.
One plan might delay payments but still charge interest. Another could offer an interest-free period. A third might add deferred interest if you don’t meet certain conditions.
For example, on a $12,000 balance at 14% annual interest, leaving the entire principal outstanding for 12 months could accumulate approximately $1,680 in simple interest. Actual charges depend on the agreement and how interest is calculated.
This difference is important because no payments doesn’t always mean no interest. Before you accept a promotional offer, ask if interest starts right away, when you’ll start making payments, and what happens if you pay off the balance early.
Canada’s Financial Consumer Agency warns that some promotional financing arrangements can become expensive when payments are missed, or the balance isn’t repaid under the agreed conditions.
Who Actually Provides Window Replacement Financing?
In most cases, the window company doesn’t lend you the money directly when you use contractor-arranged financing. Instead, they work with a bank or lending partner who reviews your application and gives you the loan.
At Ecoline, one of our financing partners is Financeit. Here’s how the process usually works:
- Request a quote for window replacement. We’ll look at your project and explain your payment options.
- Check if you qualify for financing. The first step may include a soft credit check that won’t affect your credit score.
- Go over the final agreement. Make sure you know your approved rate, repayment schedule, fees, and any credit check details.
- Get your windows installed. The installation and lender funding will follow the agreed terms.
- Start making payments. Depending on your offer, payments might begin right away or after a set deferral period.
Keep in mind, promotional terms, approval, and repayment schedules can all be different. A longer deferral might seem appealing, but it shouldn’t be the only reason you pick a financing option.
5 Questions to Ask Before Financing New Windows
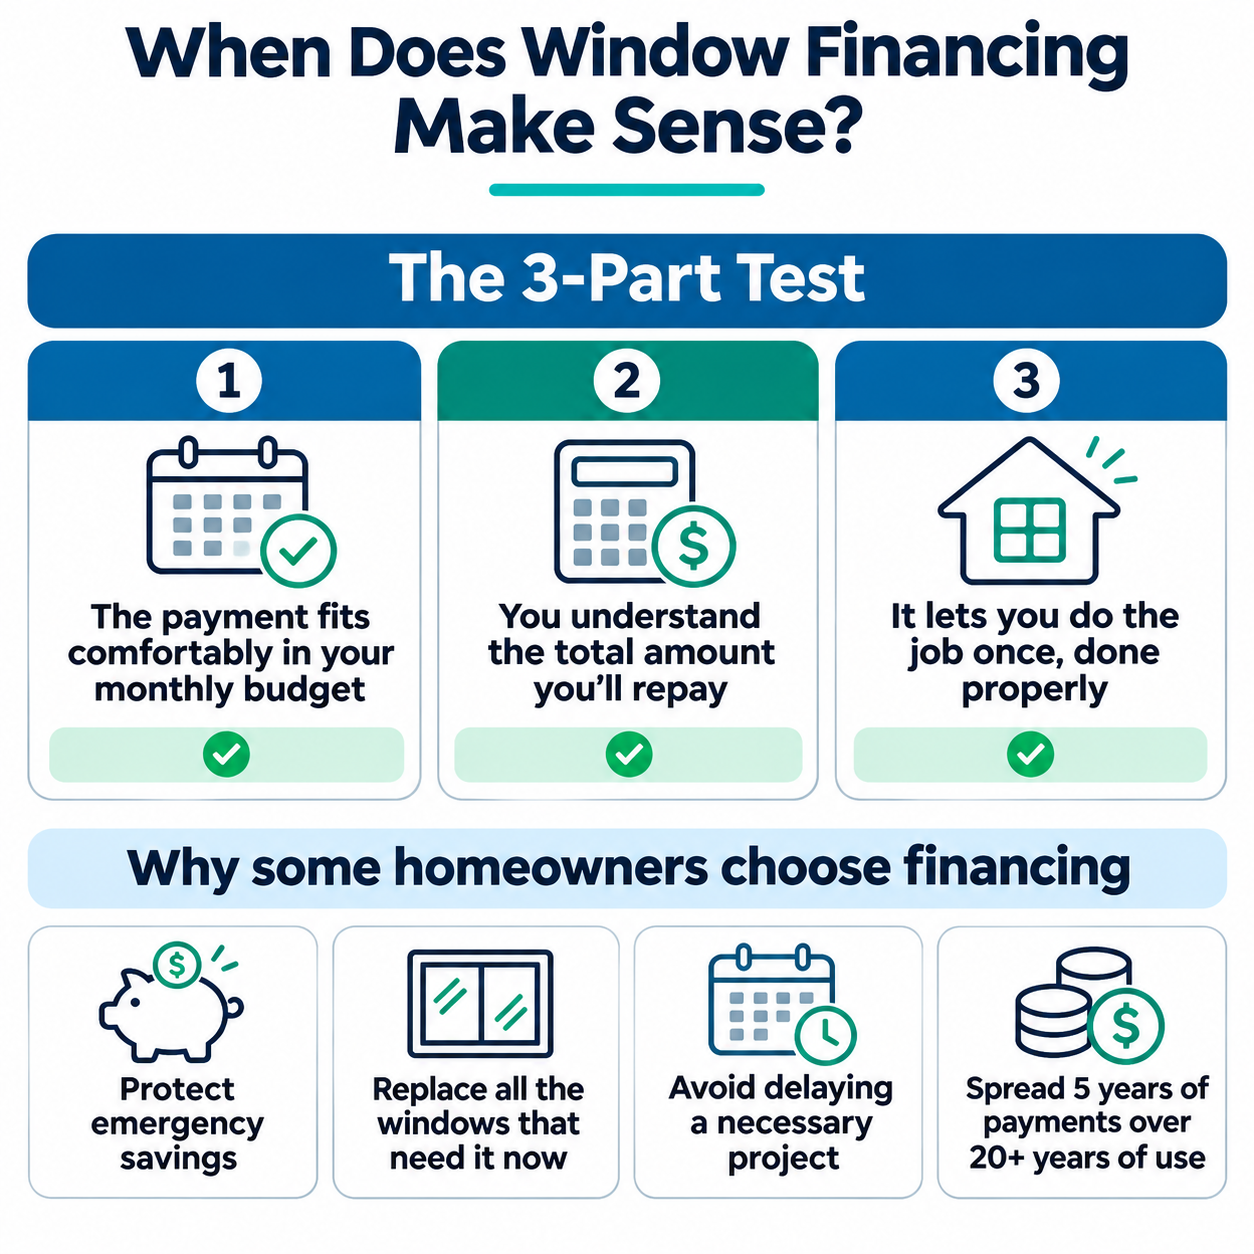
Before you sign a window replacement contract or loan agreement, make sure you can answer these five questions:
| Question | Reason to ask |
| 1. What is the total amount I’ll pay back? | A manageable monthly payment can hide thousands of dollars in interest and fees |
| 2. Does interest accumulate during the promotional period? | Twelve months without payments may still increase your borrowing cost |
| 3. Can I repay the loan early without a penalty? | Early repayment could reduce your interest expense |
| 4. When does the lender pay the contractor? | You need to understand your obligations if installation is delayed or incomplete |
| 5. What protects me if something goes wrong? | Check the written installation contract, required licensing, insurance, cancellation terms, and warranty |
You should also check if the contractor has proper liability insurance and workers’ compensation coverage, if needed. For extra protection, look up contractor requirements and your consumer rights in your province before starting a big renovation.
When is window financing not worth It?
While financing has its benefits, there are times when it’s not the best choice: if you’re able to pay for your replacement windows without dipping into your emergency savings or other important expenses, paying upfront lets you avoid borrowing costs.
Similarly, financing might not be the best choice if the monthly payments would strain your budget, the lender’s interest rate is too high, or the renovation includes upgrades you don’t really need.
Think about doing a smaller project or just the repairs you need if those options can fix the problem well enough. The right financing plan should help make a smart renovation affordable. It shouldn’t push you into taking on a project you can’t afford.
Can You Finance Window Replacement with Ecoline?
It can be worth looking into window financing even if you have enough money to pay upfront. Financing can help you keep your emergency savings intact, finish all the needed work at once, and avoid putting off improvements just because of the upfront cost.
Ecoline offers flexible payment options for eligible homeowners, like $0 down, equal monthly payments, and special payment deferrals. Our team will walk you through the financing options when you get your window replacement quote, so you can see both the installation costs and the total borrowing costs before you decide.
Shopping for new high-performing windows? Check out our financing options or ask for a free quote to find the payment plan that works for your project and budget.
1750 Coast Meridian Rd #102,
Port Coquitlam, BC V3C 6R8
100, 17866 106A Avenue,
Edmonton, AB, Canada,
T5S 1V3
3307 Dunmore Rd SE #12,
Medicine Hat, AB,
Canada, T1B 3R2
2081 Merivale Rd #201, Ottawa, ON, Canada, K2G 1G9
by appointment only
108, 55 Akerley Blvd, Dartmouth,
NS, Canada, ВЗВ 1M3